Global service revenues for High Throughput Satellites (HTS) are projected to more than double to $76 billion by 2034 as the commercial space industry enters a new era of scale and performance. According to a newly released March 2026 report from Paris-based space consulting firm Novaspace, worldwide capacity demand will surge to an unprecedented 218 Terabits per second (Tbps) over the next decade. This exponential growth is primarily driven by the rapid expansion of Non-Geostationary Orbit (NGSO) constellations and a fundamental shift in global connectivity adoption.
The Shift to Terabit Infrastructure
High Throughput Satellites represent a massive leap in orbital communications infrastructure. These advanced systems utilize frequency reuse and multiple spot beams to drastically increase data capacity and reduce the overall cost per bit. For decades, the satellite communications sector relied heavily on massive, static Geostationary Orbit (GEO) satellites positioned 36,000 kilometers above Earth.
While these legacy systems provided wide geographic coverage, they frequently suffered from high latency and limited bandwidth flexibility. Today, the telecommunications market is undergoing a fundamental structural transformation. The widespread proliferation of Low Earth Orbit (LEO) networks operating much closer to Earth has introduced low-latency, high-speed broadband to previously underserved enterprise and government sectors.
The Starlink Catalyst
The Novaspace report explicitly identifies SpaceX’s Starlink as the primary disruptor reshaping the global satellite landscape. By aggressively deploying thousands of LEO satellites, Starlink has established aggressive new industry benchmarks for pricing, performance, and deployment speed.
“Starlink’s impact has been catalytic,” said Dimitri Buchs, Manager at Novaspace. “Lower-cost capacity, rapid scaling, and improved service quality have reset expectations across the market.”
Buchs noted that the entire satcom ecosystem is now facing intense pressure to innovate and rethink long-term strategic positioning. Between 2020 and 2025, NGSO networks drove HTS service revenues up by 44 percent, expanding the market from $21.5 billion to nearly $31 billion.
GEO Operators Pivot Their Strategy
Facing unprecedented competition from agile LEO constellations, traditional GEO operators are aggressively adapting their technological and business models. To remain competitive, legacy providers are abandoning rigid, single-purpose satellite architectures.
Instead, operators are investing heavily in flexible, software-defined payloads. These advanced digital systems allow operators to reallocate bandwidth in real-time based on shifting regional demand or emergent customer needs.
Furthermore, the industry is seeing a marked shift toward small GEO platforms. These smaller, highly capable satellites require significantly lower capital expenditures (CAPEX) and boast shorter manufacturing timelines, allowing operators to deploy targeted capacity with greatly improved cost efficiency.
Surging Demand in Specialized Verticals
While consumer broadband has driven much of the recent LEO headline growth, Novaspace data indicates that the next wave of HTS revenue will stem from high-value enterprise and government applications. Land Mobility, Military Satellite Communications (MilSatCom), and Aeronautical In-Flight Connectivity (Aero IFC) are emerging as the fastest-growing market verticals.
In the aviation sector, airlines are aggressively upgrading legacy Wi-Fi systems to NGSO-powered networks. Passengers now expect terrestrial-like streaming quality at 30,000 feet, forcing airlines to secure high-capacity bandwidth contracts.
Similarly, the Land Mobility sector requires robust, uninterrupted connectivity. Emergency response fleets, remote logistics operations, and the developing autonomous vehicle market rely heavily on continuous satellite links when operating outside traditional cellular coverage zones.
Geopolitics and Sovereign Security
As global reliance on satellite infrastructure deepens, the strategic importance of secure orbital communications has intensified. The Novaspace report highlights that market differentiation is increasingly tied to spectrum strategy, advanced security architectures, and sovereign space capabilities.
In a deteriorating global security environment, resilient connectivity has transitioned from a commercial luxury to a critical national defense requirement. Governments and defense ministries are driving massive investments into MilSatCom networks designed to withstand electronic warfare, jamming, and anti-satellite threats.
Secure, encrypted bandwidth is now a primary driver of infrastructure funding. Government contracts prioritize networks that can guarantee mission-critical uptime during geopolitical crises.
The Push for Multi-Orbit Interoperability
To sustain this projected growth toward 218 Tbps, the satellite ecosystem must overcome significant technical fragmentation. Currently, many satellite networks operate in proprietary silos, requiring specialized hardware for each specific constellation.
Scaling the next phase of the terabit era will require unprecedented coordination between competing operators and hardware manufacturers. The report underscores a growing industry mandate for multi-orbit interoperability.
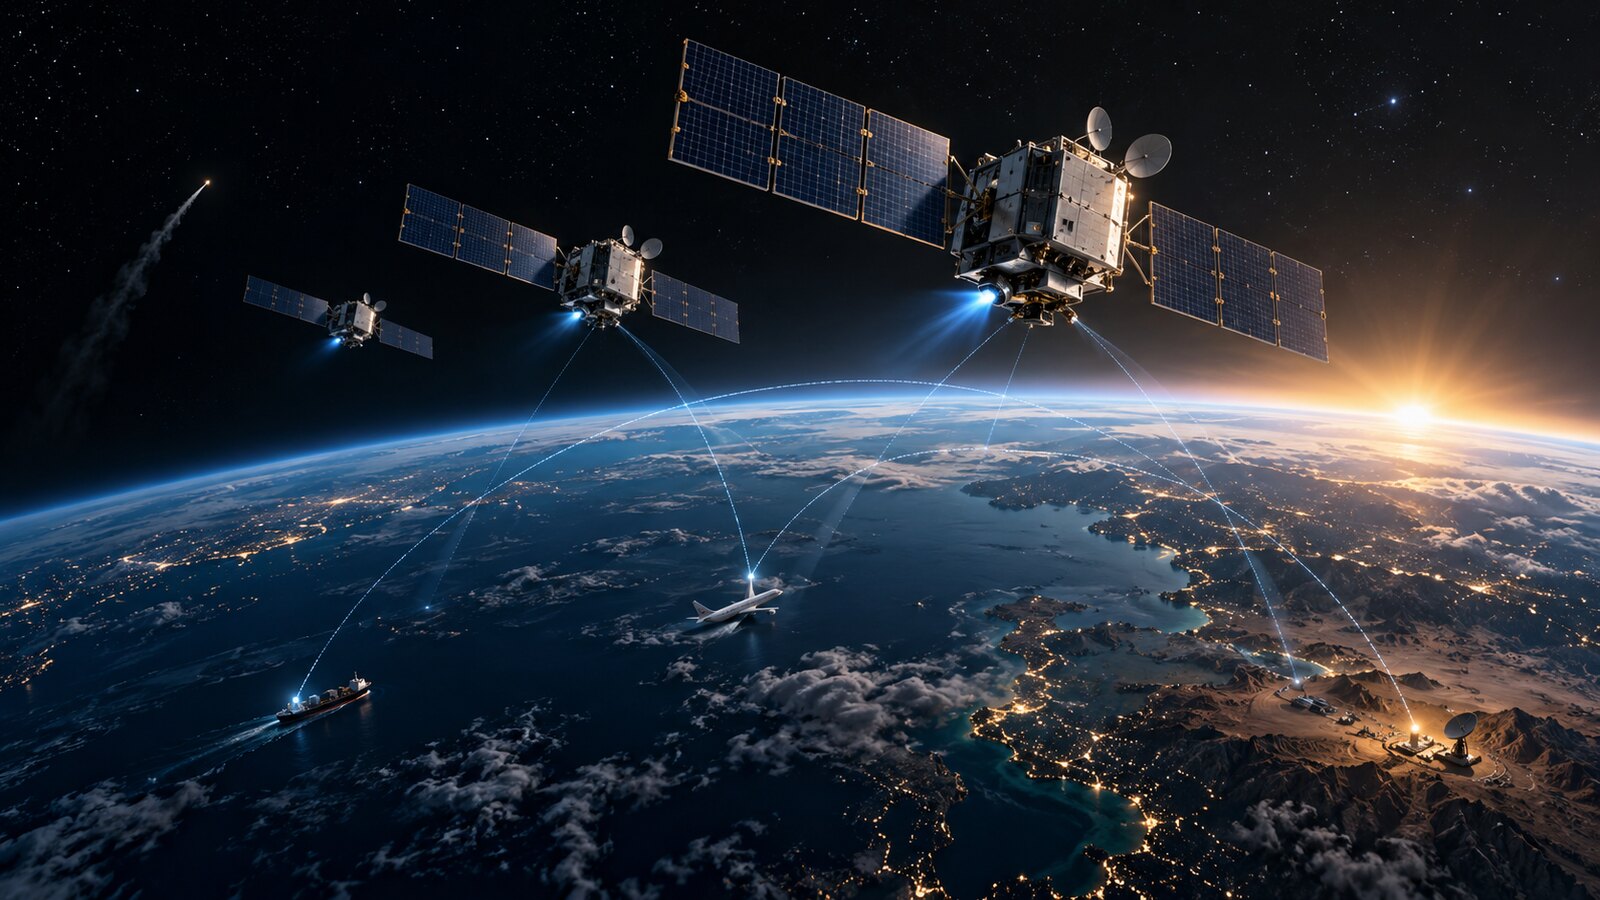
Advanced electronically steered arrays are being developed to allow user terminals to seamlessly switch between LEO, Medium Earth Orbit (MEO), and GEO networks. This dynamic switching ensures uninterrupted service based on immediate availability and specific latency requirements.
Furthermore, operators are increasingly focused on hybrid terrestrial-satellite architectures. Converging satellite networks with standard 5G and future 6G terrestrial protocols will enable more cost-effective deployments and frictionless user experiences.
Looking Ahead
The ability to execute complex, multi-layered network strategies will soon separate market leaders from legacy casualties. “In this next phase, execution will be critical,” Buchs stated. “Operators that can combine scale with flexibility—and deliver high-performance connectivity across multiple domains—will be best positioned to capture this expanding market.”
Industry watchers should monitor upcoming consolidation efforts and strategic partnerships between NGSO upstarts and established GEO operators. As the HTS market races toward the $76 billion milestone, the successful integration of multi-orbit user terminals and standardized 5G convergence will serve as the ultimate bellwether for the terabit era’s commercial success.