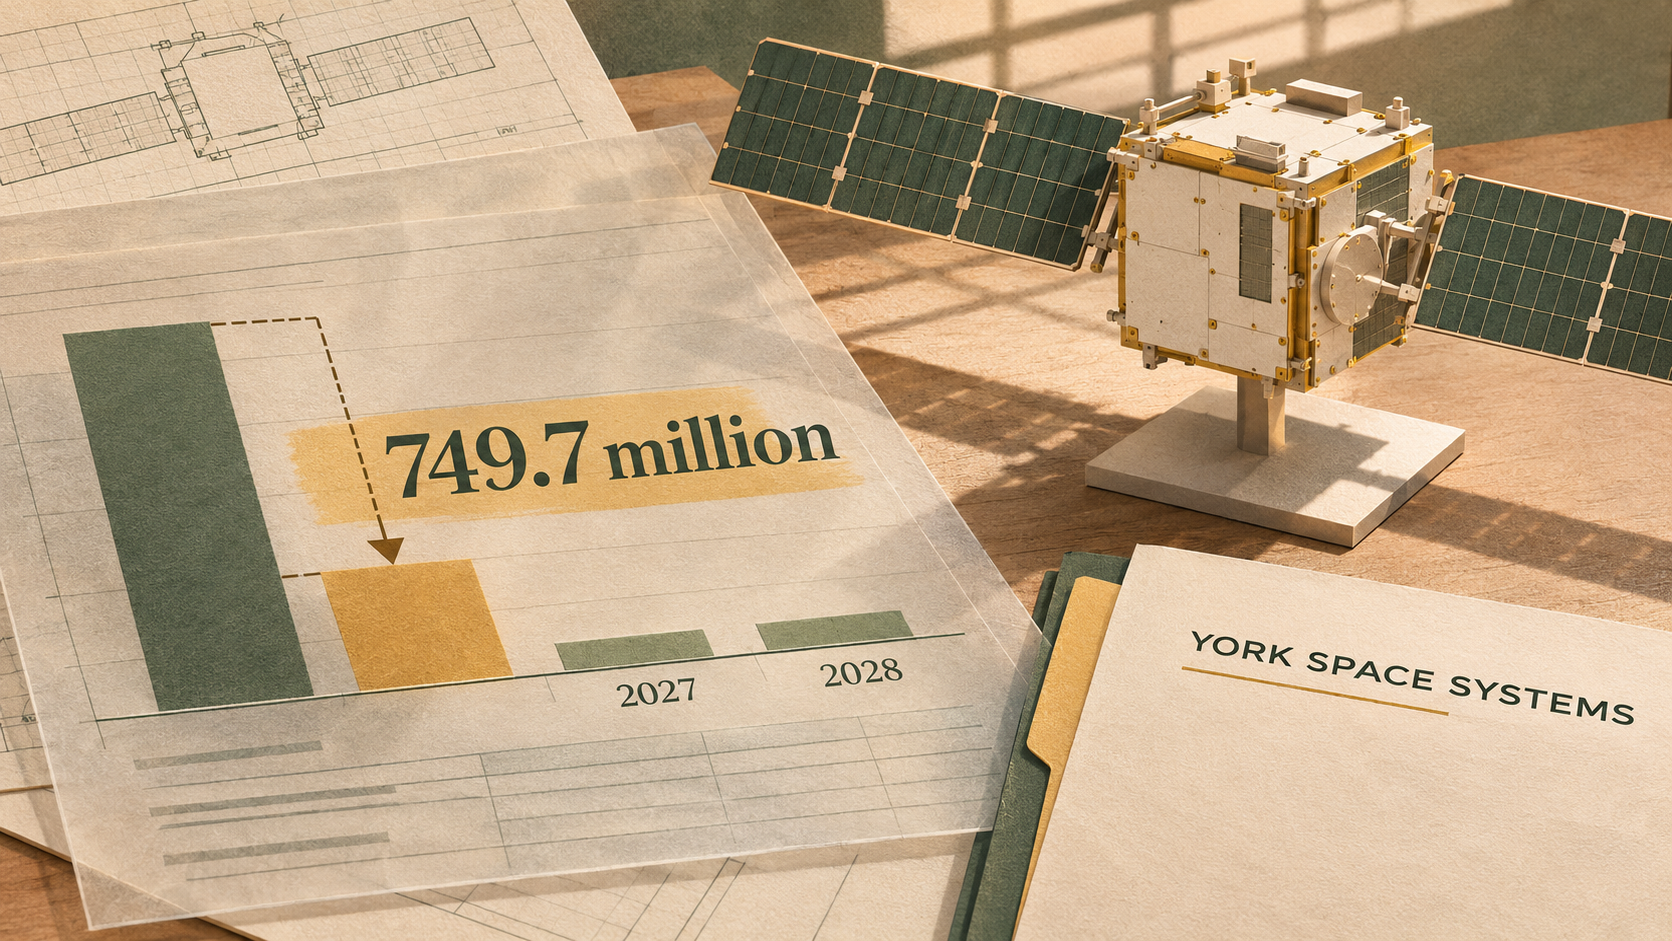
A US$749.7 million writedown can look like a business collapsing. In York Space Systems’ case, it is better read as a warning about the timing and bankability of the Pentagon’s next generation of satellite orders.
York’s charge is non-cash, and it does not mean the company lost US$749.7 million of contracts. It means management could no longer support most of the goodwill value on its balance sheet with sufficiently certain forecasts of awards beyond 2026. The distinction matters—but so does the scale.
SpaceNews first highlighted the impairment and York’s expectation that major awards will move into 2027 and 2028. For the wider space economy, the consequential development is the repricing behind the accounting: access to a Pentagon contract vehicle is no longer being valued like a predictable satellite production order.
A non-cash charge with a real signal
York’s 12 November filing with the US Securities and Exchange Commission reported third-quarter revenue of US$84.2 million, down 7% year on year, and gross profit of US$15.5 million, down 23%. The company posted a US$807.4 million net loss, dominated by the impairment, while adjusted EBITDA—a company-defined non-GAAP measure—was negative US$27.6 million.
The impairment was nearly nine times quarterly revenue. It does not drain cash today, but it acknowledges that projected future cash flows no longer justify the previous carrying value. York said the trigger was difficulty estimating “with sufficient certainty” the timing and amount of future awards after 2026. On its earnings call, management also pointed to an earlier revenue reduction and a share price below book value.
York still had US$309 million in cash and an undrawn US$150 million revolving facility at 30 September. Its backlog was US$581 million. Those figures temper immediate liquidity concerns, but they should not be confused with management’s US$14.9 billion “identified pipeline”, which grew 30% during the quarter. Backlog reflects awarded agreements; the pipeline is a company estimate of potential opportunities and is neither funded revenue nor a forecast of wins.
The Pentagon is changing the unit of competition
York built its position by winning large Space Development Agency production lots, including 42 Tranche 1 Transport Layer satellites and 62 Tranche 2 Alpha spacecraft. That model gave manufacturers visibility: a competitive award converted directly into a substantial block of satellites, ground work and operations.
The emerging model is more conditional. York says the government is using more indefinite-delivery, indefinite-quantity vehicles and prototype agreements, with smaller entry awards followed by task orders. This can accelerate purchases once a supplier is qualified, but it transfers timing risk to industry. A place on a vehicle is an option to compete, not production volume.
The Space Data Network illustrates the split. Space Systems Command awarded SpaceX a US$2.29 billion delivery order for the backbone, while later funding five companies with complementary US$12 million contract-and-agreement sets to demonstrate multi-vendor connectivity. York secured two Space Data Network task orders, but did not disclose their individual value in its quarterly release.
Strategically, the architecture promises resilience and standardised interfaces. Commercially, it can produce a winner-takes-most backbone surrounded by smaller integration and demonstration awards. “Vendor diversity” therefore does not guarantee evenly distributed revenue.
Why the risk extends beyond York
Space manufacturers have invested in factories, staff and supply chains on the assumption that proliferated constellations will refresh frequently. If block orders become task-order pipelines, suppliers must carry capacity for longer before revenue arrives. That raises working-capital needs, weakens operating leverage and makes acquisition-funded expansion harder to defend.
It also changes valuation. Investors should discount contract ceilings, pipeline totals and vehicle selections more heavily than funded backlog. Companies with diversified defence portfolios can absorb schedule movement across programmes; focused spacecraft manufacturers feel it directly. The likely responses are more joint ventures, selective consolidation and a sharper premium on commercial contracts that genuinely diversify government exposure.
The technical cause of some delay cannot be ignored. A 2026 US Government Accountability Office review found that the Space Development Agency had overestimated the readiness of some critical missile-tracking technologies, lacked an architecture-level schedule and faced additional unplanned contractor work. Air & Space Forces Magazine reported that Tranche 3 launches are expected in late 2028 or 2029 as the agency moves towards an enterprise model and expands its ground architecture.
That creates a genuine procurement tension. The Pentagon wants faster iteration, open interfaces and more suppliers, while integration and test evidence argue for caution before buying at scale. The result may be a healthier architecture, but the transition is financially awkward for the industrial base expected to build it.
The recovery case is plausible, not proven
York’s management remains bullish. It argues that its contract positions, production record and 30% pipeline growth set up larger awards in 2027 and beyond. It also points to a US$187 million Tomorrow.io commercial contract, subsidiaries spanning ground networks, terminals, propulsion and solar technology, and expansion into unmanned systems.
Those are company claims and strategic options, not proof that delayed military awards will convert on schedule. Acquisitions can diversify revenue, but they also add integration cost, inventory and execution risk. The quarter’s negative adjusted EBITDA shows that the business still needs operating improvement even when the non-cash impairment is removed.
Milestones that will determine the verdict
The first test is task-order conversion: disclosed value, funded scope and delivery timing matter more than additions to the pipeline. The second is whether backlog grows without margin deterioration as Tranche 2 work advances. Investors should also watch cash use, acquisition integration and whether the Tomorrow.io programme becomes a repeatable commercial line rather than a one-off counterweight.
At programme level, the milestones are the fiscal 2027 appropriations outcome, additional Space Data Network suppliers and task orders, Tranche 3 ground-system awards, and credible launch and integration schedules for 2028–29. Successful cross-vendor optical networking would strengthen the multi-supplier case; persistent integration delays would favour larger primes and vertically integrated operators.
York’s writedown is therefore not a verdict on proliferated military space. It is a valuation reset for the gap between strategic demand and contractable revenue. The opportunity remains large. The market has simply been reminded that a government architecture, an IDIQ position and a funded production order are three different assets.